50/30/20 budget calculator
Enter your take-home pay and your spending to see how close you are to 50% needs, 30% wants and 20% savings.
- Free, no sign-up
- Prints on Letter or A4
- Stays on your device
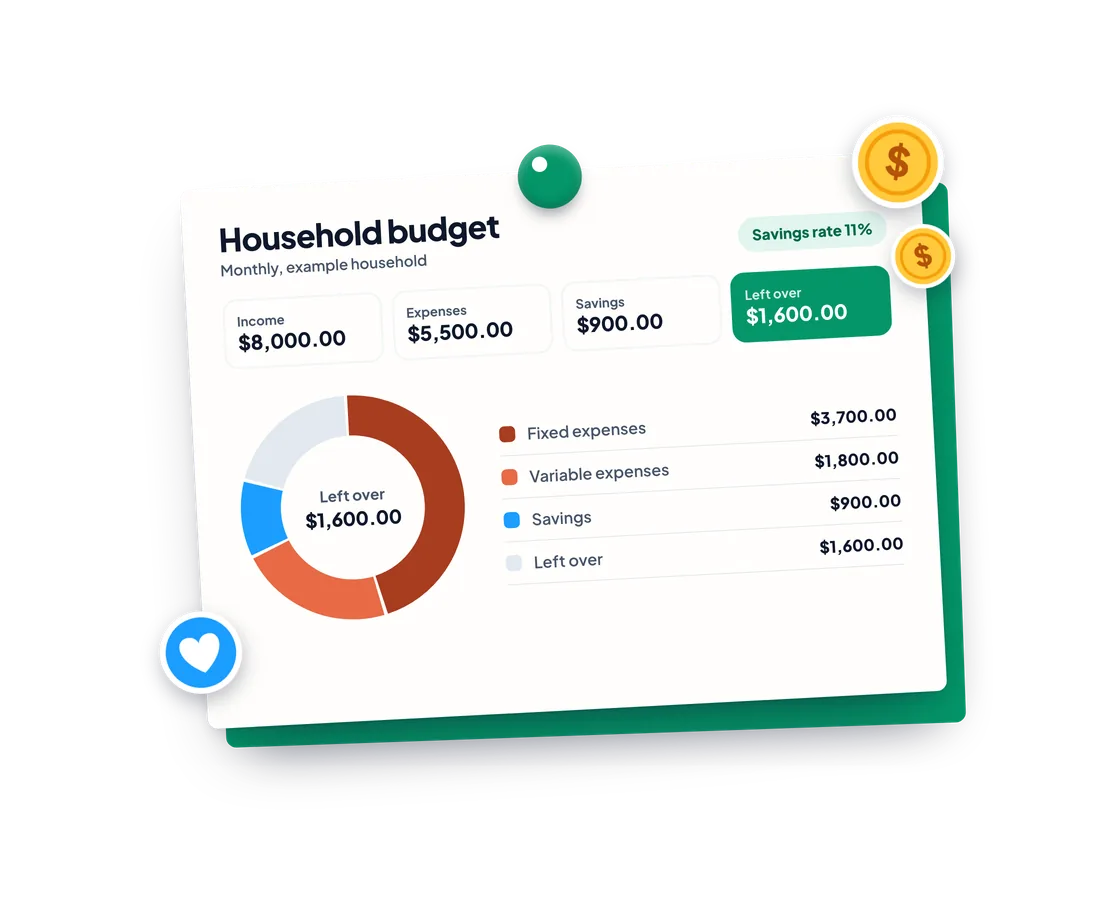
This is an example household. Change anything, or clear it to start your own.
Changing the currency changes the formatting only. Amounts are not converted.
Income
$3,500.00
$42,000.00 a year
Expenses
$2,480.00
$29,760.00 a year
Savings
$600.00
$7,200.00 a year
Left over
$420.00
$5,040.00 a year
Savings rate
17%
Income
Salary
Fixed expenses
Rent or mortgage
Utilities
Insurance
Phone and internet
Variable expenses
Groceries
Transport
Dining out
Entertainment
Savings
Emergency fund
Retirement
Where the money goes
- Fixed47%
- Variable24%
- Savings17%
- Left over12%
Monthly amount by line
- Rent or mortgage$1,300.00
- Utilities$150.00
- Insurance$100.00
- Phone and internet$80.00
- Groceries$400.00
- Transport$200.00
- Dining out$150.00
- Entertainment$100.00
- Emergency fund$300.00
- Retirement$300.00
50/30/20: a common rule of thumb
About 50% of income for needs, 30% for wants and 20% for saving. Here is how your fixed, variable and savings shares compare.
- Fixed (needs)47% · target 50%On track
- Variable (wants)24% · target 30%On track
- Savings17% · target 20%Under
This is a rule of thumb for thinking, not financial advice. Every household is different.
Your draft is saved on this device only.
Monthly household budget
| Line | Amount | How often | Per month |
|---|---|---|---|
| Income | |||
| Salary | $3,500.00 | Monthly | $3,500.00 |
| Fixed expenses | |||
| Rent or mortgage | $1,300.00 | Monthly | $1,300.00 |
| Utilities | $150.00 | Monthly | $150.00 |
| Insurance | $100.00 | Monthly | $100.00 |
| Phone and internet | $80.00 | Monthly | $80.00 |
| Variable expenses | |||
| Groceries | $400.00 | Monthly | $400.00 |
| Transport | $200.00 | Monthly | $200.00 |
| Dining out | $150.00 | Monthly | $150.00 |
| Entertainment | $100.00 | Monthly | $100.00 |
| Savings | |||
| Emergency fund | $300.00 | Monthly | $300.00 |
| Retirement | $300.00 | Monthly | $300.00 |
- Income
- $3,500.00
- Expenses
- $2,480.00
- Savings
- $600.00
- Left over
- $420.00
Everything runs in your browser. Nothing you enter is sent anywhere.
Your budget is ready. Want to track it through the month?
Domus tracks your household's budget as it happens, together.
- PlusA shared household budget with recurring entries
- PlusAccounts and monthly and yearly reports
- PlusSnap a receipt to log it

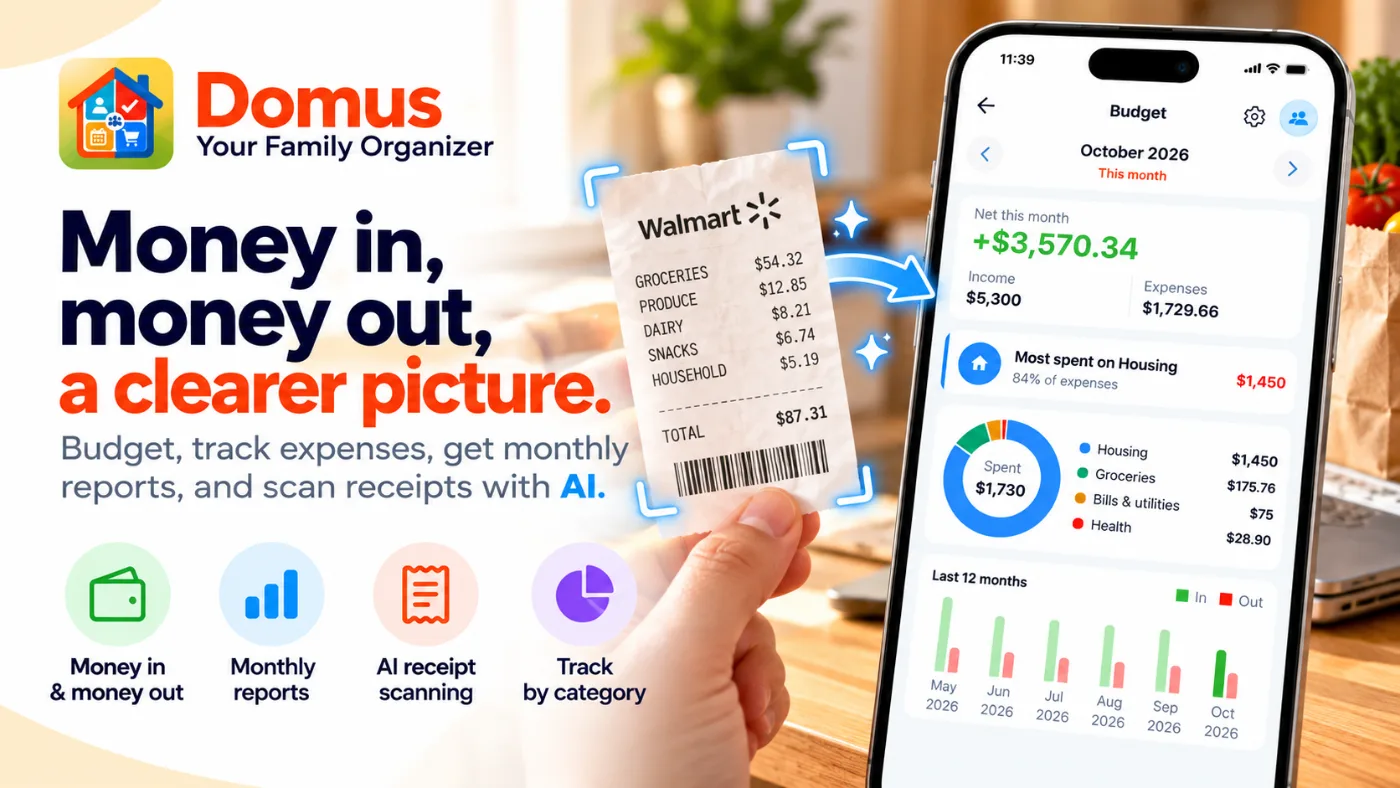
Keep it going in the Domus app
Open this budget on your phone and share it with your household.
Sends this budget to Domus so you can open it in the app. Deleted after 7 days.
How to use it
Enter your income lines and pick how often each one is paid: weekly, every 2 weeks, twice a month, monthly, quarterly or yearly.
Fill in your fixed, variable and savings lines, then add, rename or remove lines to match your household. Pick your currency at the top.
Read the monthly totals, what is left over, your savings rate and the charts, then print the report or download the spreadsheet.
Examples
Checking a single budget
Enter your monthly pay after tax, then your rent, bills and groceries as fixed costs and the rest as variable. The 50/30/20 check shows at once whether needs or wants run over.
A couple sharing costs
Add both salaries as income lines and list the shared bills once. The percentages then describe the household, not one person.
Finding 20% to save
Add a savings line at 20% of your pay and see what is left. If the remainder turns negative, the wants share is where to look first.
The 50/30/20 rule splits take-home pay into three parts: about 50% for needs such as rent, utilities, insurance and groceries, about 30% for wants such as eating out and entertainment, and about 20% for savings and paying down debt.
In this calculator, fixed bills count as needs and variable spending counts as wants. The results show each share of your income and flag a share that runs over its target.
Treat the split as a starting point, not a rule. Where rent is high, needs often take more than half; the useful question is where the difference comes from.
Frequently asked questions
How do I turn biweekly pay into a monthly amount?
Pick Every 2 weeks on the income line. Biweekly pay comes 26 times a year, so the calculator multiplies by 26 and divides by 12. That is slightly more than two paychecks a month, because two months a year contain a third paycheck. Weekly pay uses 52 divided by 12, and twice a month uses exactly 2.
What is the 50/30/20 rule?
It is a common rule of thumb that suggests about 50% of income for needs, 30% for wants and 20% for saving. The calculator compares your fixed, variable and savings shares with those targets. It is a starting point to think with, not financial advice, and plenty of households reasonably land elsewhere.
What counts as fixed and what counts as variable?
Fixed expenses are about the same every period and are hard to change in the short term: rent or mortgage, insurance, utilities, phone and childcare. Variable expenses move with your choices: groceries, transport, dining out and entertainment. If a cost sits in between, put it where it behaves most like your own bills.
How do I budget for yearly or irregular bills?
Add the bill as a yearly line, or quarterly if that is how it arrives. The calculator divides it into a monthly amount, which is what you would set aside each month in a sinking fund so the bill is already covered when it lands.
Is my data stored or uploaded?
Nothing is uploaded. The calculator runs in your browser and saves your draft on this device only, so it is still there when you come back. Use the Clear button to remove it.
Does changing the currency convert my amounts?
No. There is no currency conversion. Changing the currency only changes how amounts are formatted, so 1,000 stays 1,000 in whichever currency you pick.
What if I have no income entered?
The calculator still adds up your spending and savings. It cannot show shares of income or a savings rate without income, so those stay empty instead of dividing by zero.
Is this financial advice?
No. It is a calculator for planning. It does not know your debts, taxes or goals, and the 50/30/20 rule is only a common rule of thumb.
How does the 50 30 20 rule work?
It is a rule of thumb for splitting take-home pay: 50% on needs, 30% on wants and 20% on savings or extra debt payments.
Is the 50/30/20 rule based on gross or net income?
On take-home pay, the amount that reaches your account after tax. Enter that figure as your income.
What if my needs are more than 50%?
That is common where housing costs are high. Keep savings as close to 20% as you can and trim wants first; the split is a guide, not a pass or fail.
Is my budget saved or shared?
It stays on your device. Nothing is uploaded, and the Clear button removes it.
More free tools and guides
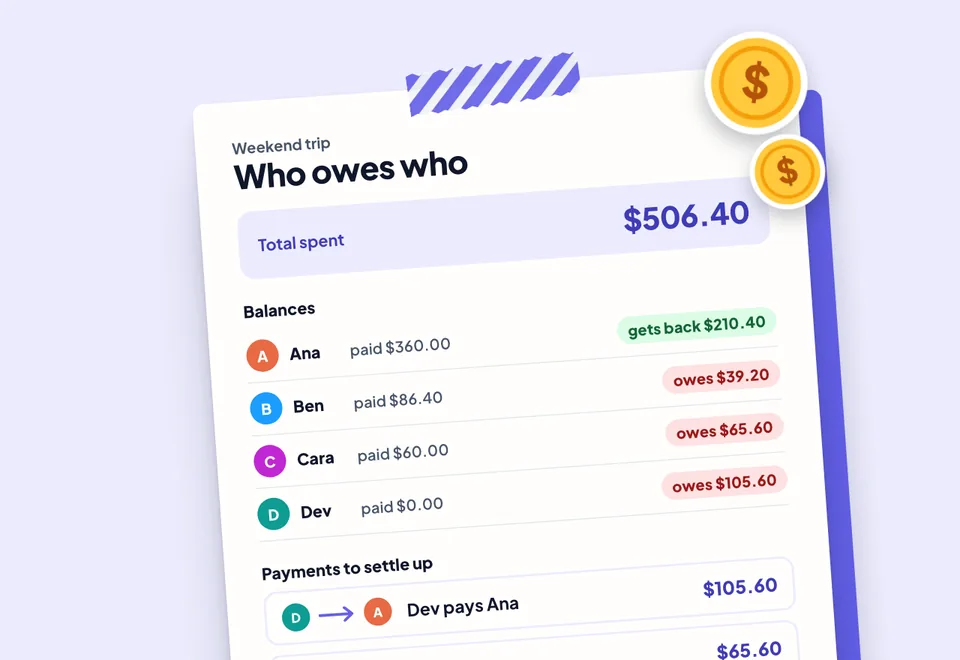
Keep it going with your household
Domus is the shared family organizer behind these tools. Download it free on iOS and Android.